- calendar_today August 18, 2025
Higher Borrowing Costs Challenge Growth, but Market Fundamentals Improve
Introduction
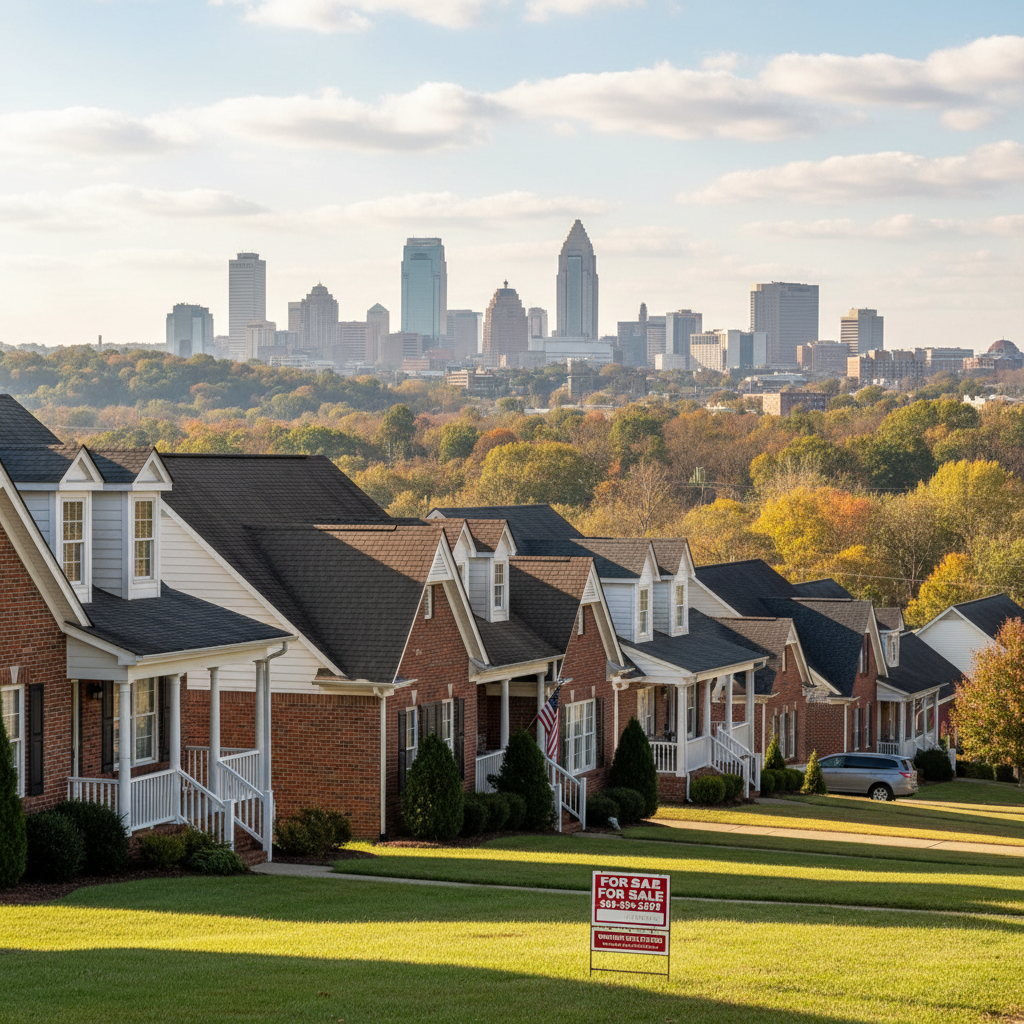
The Atlanta Federal Reserve’s recent estimate—forecasting only a single interest rate cut in 2025—is triggering a cautious but wise response from Kentucky’s real estate sector. As the Bluegrass State is enjoying strong demand for housing, commercial development, and farmland, the prolonged era of high interest rates is finally beginning to influence investment activity, development projects, and home purchasing confidence.
With Louisville, Lexington, and Bowling Green registering tempered activity, market participants are reassessing their financials in a situation driven by costlier borrowing and tighter credit.
Housing Market Faces Affordability Problem
Rising mortgage rates have already begun slowing Kentucky’s real estate housing market, where affordability is a central issue. The Fed’s conservative expectations of rate reductions signal the slowing trend will continue until 2025.
Most Crucial Housing Market Trends
- Affordability Pressure: Increasing mortgage costs are making monthly payments harder and harder to afford for first-time homebuyers and middle-class families.
- Switch to Rentals: As purchasing power declines, renters are seeking out multi-family properties and rent properties in growing numbers, especially in urban locations.
- Slower Sales Volume: Houses are staying longer on the market and competitive bidding has slowed down, giving buyers a little more negotiating power—if they can find financing.
Despite higher interest rates, though, the commonwealth’s more affordable living versus national rates bodes well with out-of-state migrants as an attractive spot for them, perhaps mitigating long-term demand.
Commercial Real Estate and Development Trends
The commercial real estate market within Kentucky has remained healthy despite higher interest rates—even rising sectors in industry, logistics, and warehouses. However, the Fed outlook will undoubtedly curtail some portion of the speed in various areas of development.
Commercial Real Estate:
- Backlog Projects: Builders can delay or scale back future building projects, particularly in areas like Northern Kentucky and Central Kentucky where the expansion of infrastructure has been strong.
- Industrial Stability: The market for warehouses and distribution facilities is stable, driven by the growth in e-commerce and strategic logistical advantages that Kentucky provides.
- Retail and Office Transformation: Mixed-use properties are transforming based on changes in purchasing habits, emphasizing adaptable space and localized services.
Even while there is guarded optimism, higher capital costs can lead developers to renegotiate deals, investigate joint ventures, or delay timelines until interest rates begin to ease.
Agricultural Land and Rural Properties Navigate Through Financing Difficulty
Kentucky’s agricultural-based economy—a cornerstone of the state’s image—is particularly vulnerable to prolonged high interest rates. Farm loans, essential for seasonal production, land acquisition, and equipment leasing, are becoming increasingly expensive and harder to secure.
Issues Confronting Rural and Agricultural Real Estate:
- Increased Cost of Finance: Small and medium-sized farms are under stress, especially those with heavy reliance on seasonal credit and variable-rate loans.
- High Land Prices: Amidst rising lending costs, agricultural land prices are continuing to sustain themselves because it is scarce in supply and still in demand steadily.
- Technology Investments Slow Down: Investment plans toward upgrading and emerging farm technology are put on the backburner because of insufficient funds.
Nonetheless, countryside property retains its long-term desirability for institutional investors as well as family firms that can ride out transient rate pressure.
What Lies Ahead for the Real Estate of Kentucky?
While the Atlanta Fed’s conservative rate-cut projection may temper expectations, Kentucky’s real estate fundamentals are still sound. Inexpensive land, a growing labor pool, and out-migration from high-cost states still drive interest in the state’s housing and commercial property markets.
Strategic Implications for Stakeholders:
- Buyers: May be forced to adjust budgets or seek alternative financing agreements, such as adjustable-rate mortgages or seller concessions.
- Developers: Must focus on demand-based developments like logistic centers and workers’ housing with an eye toward construction costs.
- Investors: Can find opportunities in long-term rental homes, commercial warehousing, and agriculture, provided the risk is adequately managed.
A diversified Kentucky economy and low-barrier access points place Kentucky in the best position to weather the impact of slow monetary relaxation. Financial elasticity, timely moves, and a focus on long-term growth will be the trump cards.
Conclusion
The Atlanta Federal Reserve’s single-rate-cut prediction for 2025 presents challenges and opportunities for Kentucky’s real estate market. From city houses to country fields, all markets are feeling the sting of expensive borrowing—but resiliency, flexibility, and affordability continue to be the state’s real estate mantra.
With developers, investors, and buyers waiting longer for relief in interest rates, Kentucky’s value proposition—founded in economic stability and future growth potential—remains a draw for those willing to wait for the long term.